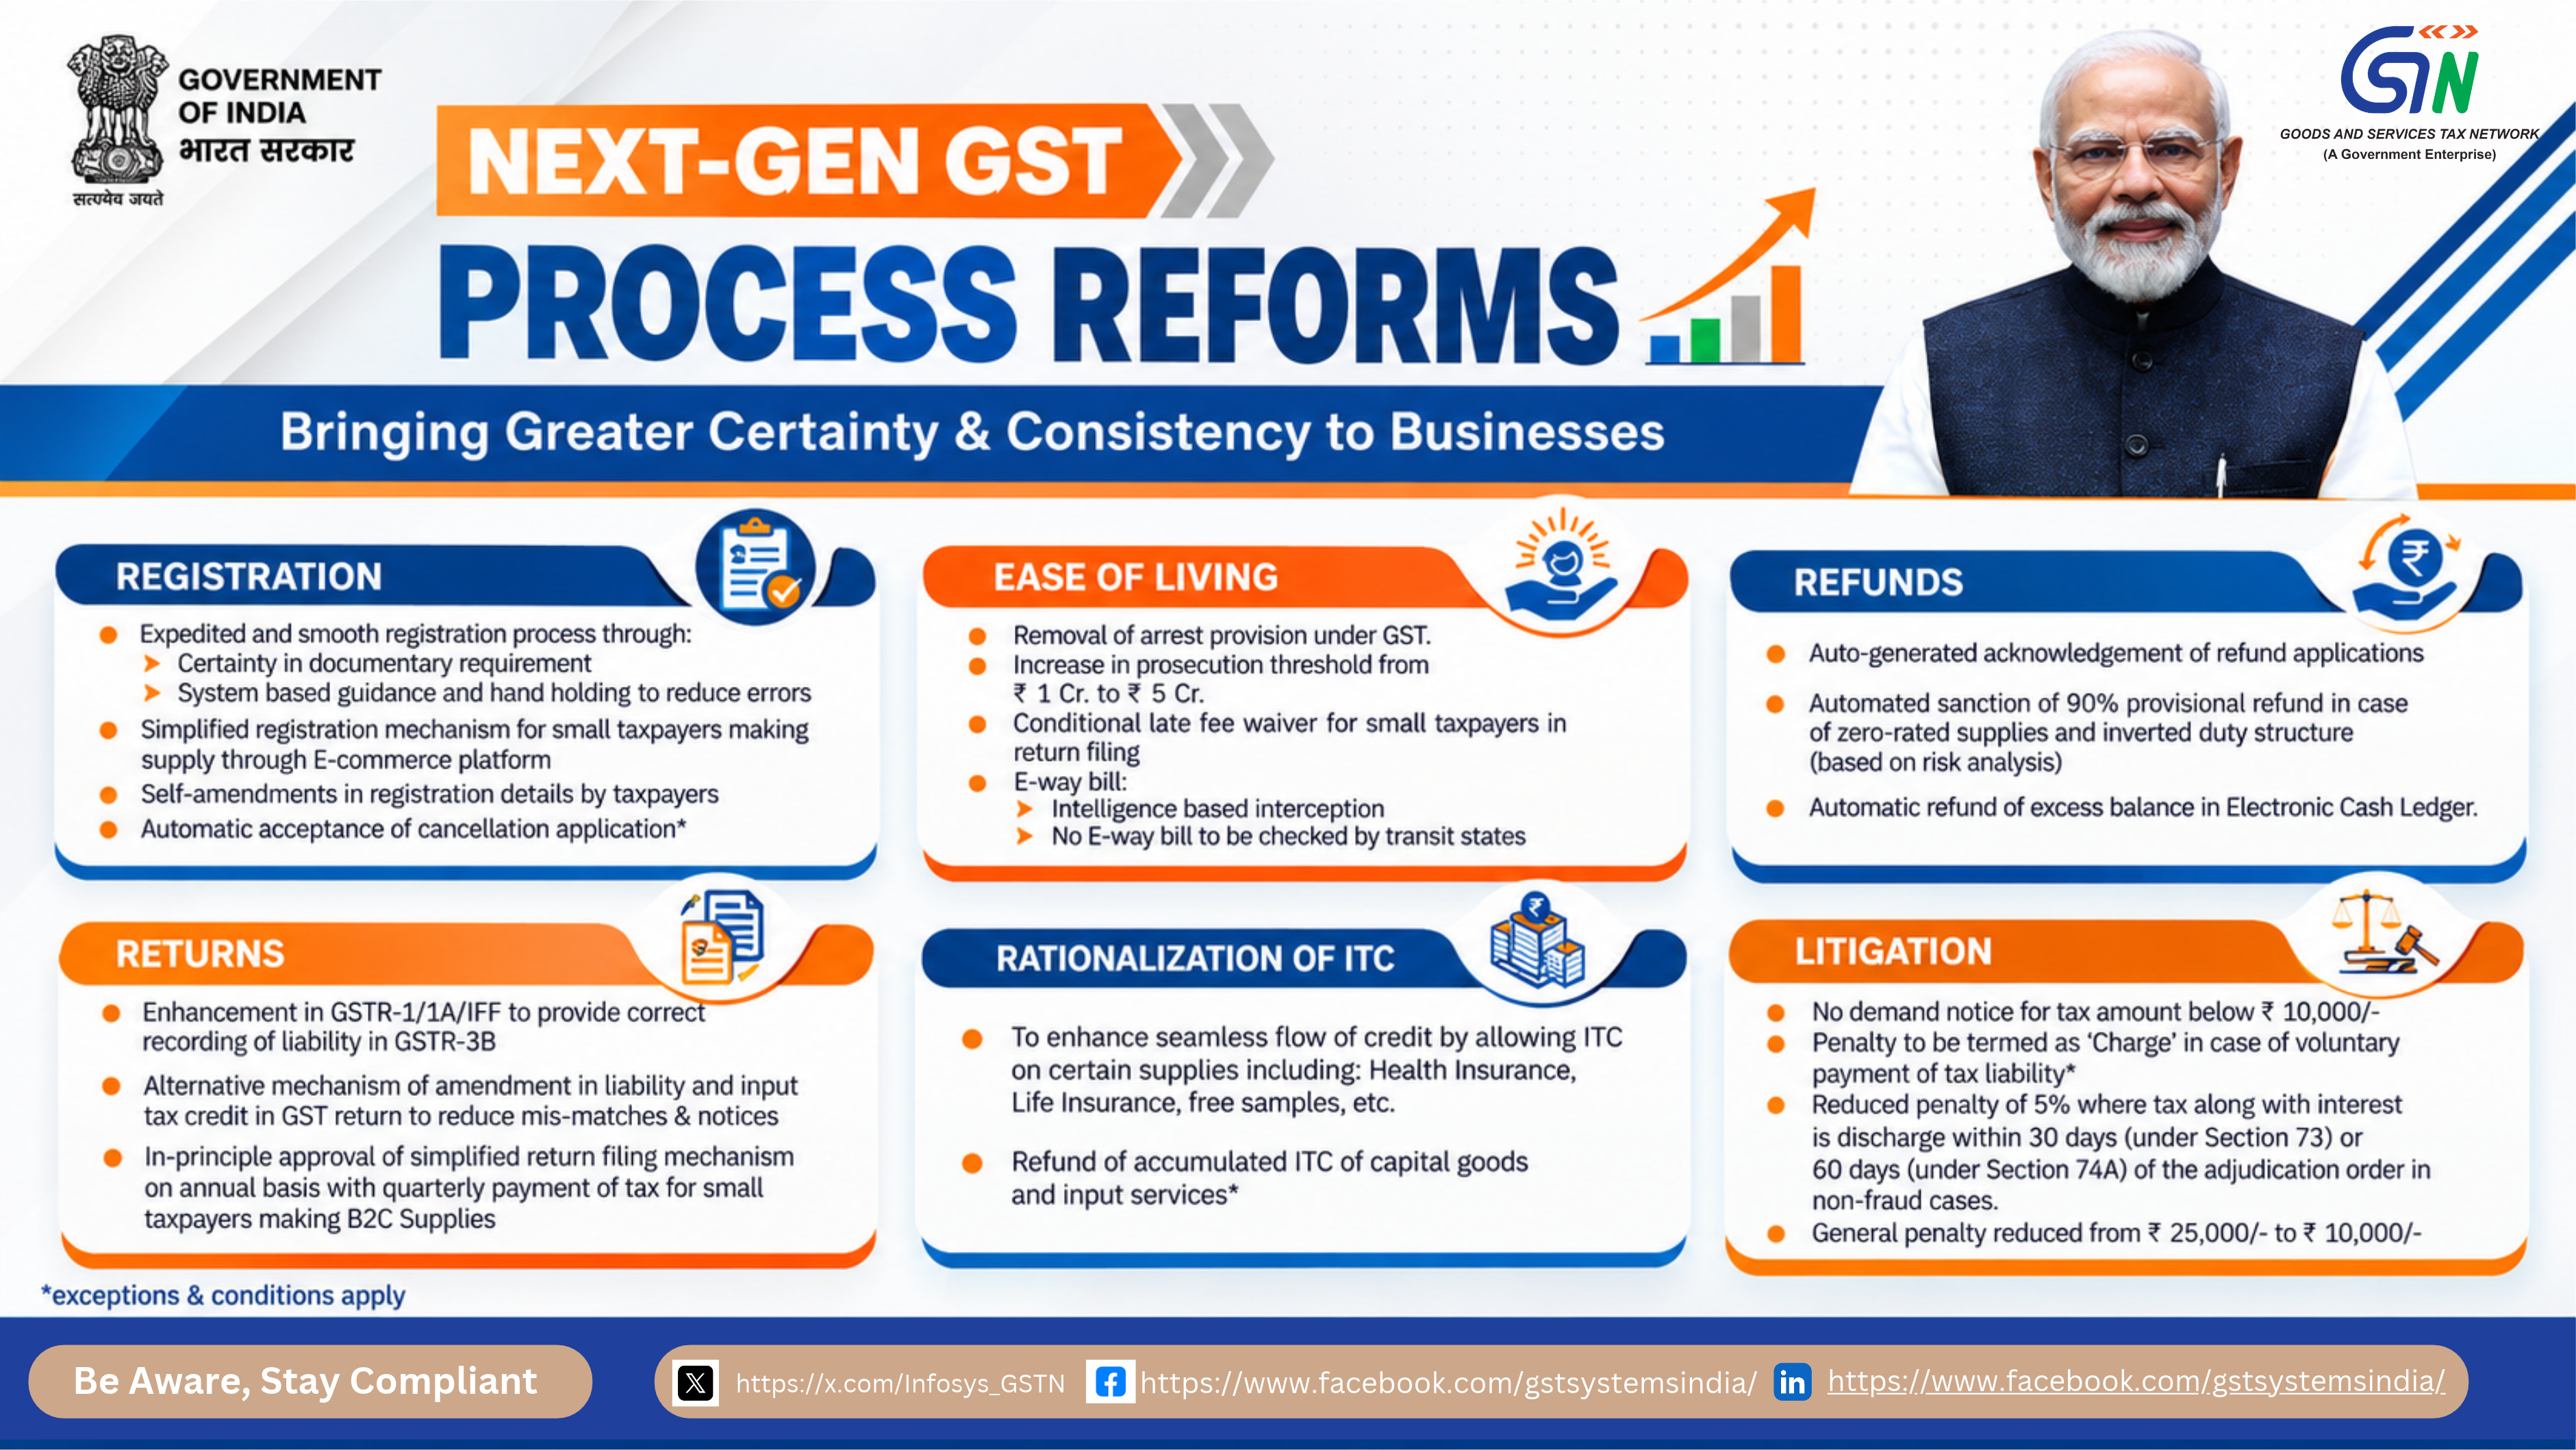
Next Gen GST Process Reforms
REGISTRATION
● Expedited and smooth registration process through: ➤ Certainty in documentary requirement ➤ System based guidance and hand holding to reduce errors
● Simplified registration mechanism for small taxpayers making supply through E-commerce platform
● Self-amendments in registration details by taxpayers
● Automatic acceptance of cancellation application*
EASE OF LIVING
● Removal of arrest provision under GST.
● Increase in prosecution threshold from ₹ 1 Cr. to ₹ 5 Cr.
● Conditional late fee waiver for small taxpayers in return filing
● E-way bill: ➤ Intelligence based interception ➤ No E-way bill to be checked by transit states
REFUNDS
● Auto-generated acknowledgement of refund applications
● Automated sanction of 90% provisional refund in case of zero-rated supplies and inverted duty structure (based on risk analysis)
● Automatic refund of excess balance in Electronic Cash Ledger.
RETURNS
● Enhancement in GSTR-1/1A/IFF to provide correct recording of liability in GSTR-3B
● Alternative mechanism of amendment in liability and input tax credit in GST return to reduce mis-matches & notices
● In-principle approval of simplified return filing mechanism on annual basis with quarterly payment of tax for small taxpayers making B2C Supplies
RATIONALIZATION OF ITC
● To enhance seamless flow of credit by allowing ITC on certain supplies including: Health Insurance, Life Insurance, free samples, etc.
● Refund of accumulated ITC of capital goods and input services*
LITIGATION
● No demand notice for tax amount below ₹ 10,000/-
● Penalty to be termed as ‘Charge’ in case of voluntary payment of tax liability*
● Reduced penalty of 5% where tax along with interest is discharge within 30 days (under Section 73) or 60 days (under Section 74A) of the adjudication order in non-fraud cases.
● General penalty reduced from ₹ 25,000/- to ₹ 10,000/-
*exceptions & conditions apply